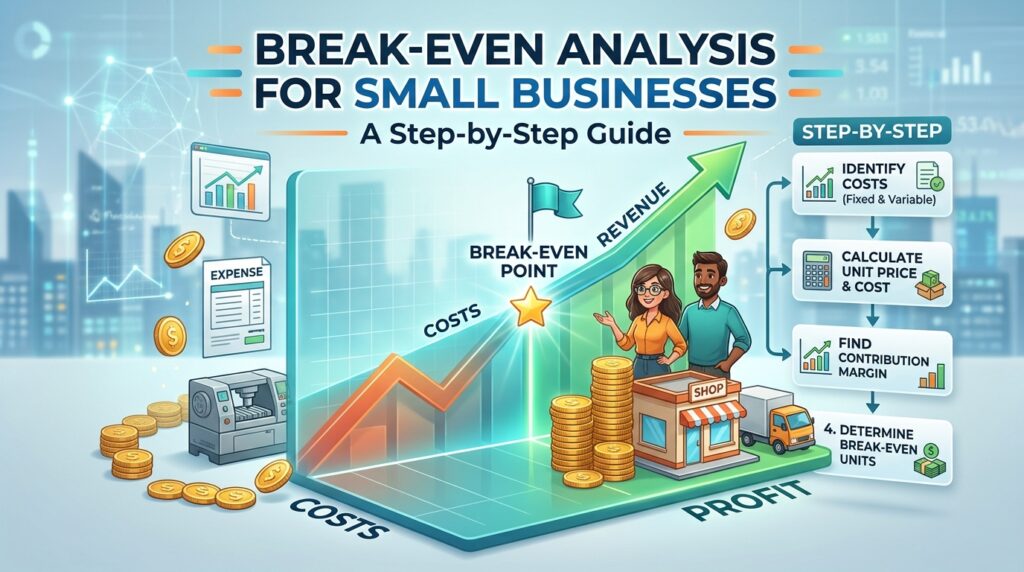
Your break-even point is the sales volume at which revenue exactly covers costs. Below it, every month loses money. Above it, every extra sale is profit. Finding it takes three numbers and one division.
The three inputs
- Fixed costs: what you pay regardless of sales, such as rent, salaries, insurance and software.
- Price per unit: what a customer pays.
- Variable cost per unit: what each extra unit costs to make and deliver, such as ingredients, packaging, shipping and card fees.
Contribution: the key idea
Each sale contributes price minus variable cost toward fixed costs. Once enough sales have covered the fixed costs, contribution becomes profit.
break-even units = fixed costs ÷ (price − variable cost)
A small bakery
Fixed costs are $6,500 a month. A loaf sells for $4.50 and costs $1.90 in ingredients and packaging.
- Contribution per loaf: $4.50 − $1.90 = $2.60
- Break-even: $6,500 ÷ $2.60 = 2,500 loaves a month
- Break-even revenue: 2,500 × $4.50 = $11,250
Adding a profit target
Break-even is the floor, not the goal. Add the profit you want to the fixed costs. For $2,000 of monthly profit, the bakery needs ($6,500 + $2,000) ÷ $2.60 = 3,269.23, so 3,270 loaves, about $14,715 of revenue.
The levers, ranked
Price
Raising the price to $5.00 lifts contribution to $3.10 and cuts break-even to 2,097 loaves, about 400 fewer. Small price changes move break-even a lot because they fall straight into contribution.
Variable cost
Cutting variable cost works the same way, but supplier savings are often harder to find than a modest price rise.
Fixed costs
Lower fixed costs reduce break-even in direct proportion. Cutting $650 a month (10%) drops break-even by 250 loaves.
Common mistakes
- Forgetting payment fees and shipping in the variable cost.
- Leaving out your own salary from fixed costs, which makes the business look healthier than it is.
- Using a price before discounts. Use the average price actually received.
- Treating it as a one-off. Recalculate whenever costs or prices change.
When a product can never break even
If the variable cost is at or above the price, each sale loses money and volume makes things worse. The fix is price or cost, never more sales.
Break-Even CalculatorUnits and revenue needed to cover fixed costs, or to hit a profit target.Open calculatorFrequently asked questions
How do I handle several products?
Use a weighted average contribution based on your typical sales mix, or calculate each product separately with a share of fixed costs.
Is break-even the same as payback period?
No. Payback asks how long it takes to recover an upfront investment. Break-even asks how much you must sell each period to cover running costs.