When you owe on several accounts, every extra dollar has to go somewhere. The two best-known strategies send it to different places. One minimises interest. The other maximises momentum. Here is how they compare on identical debts.
The two methods
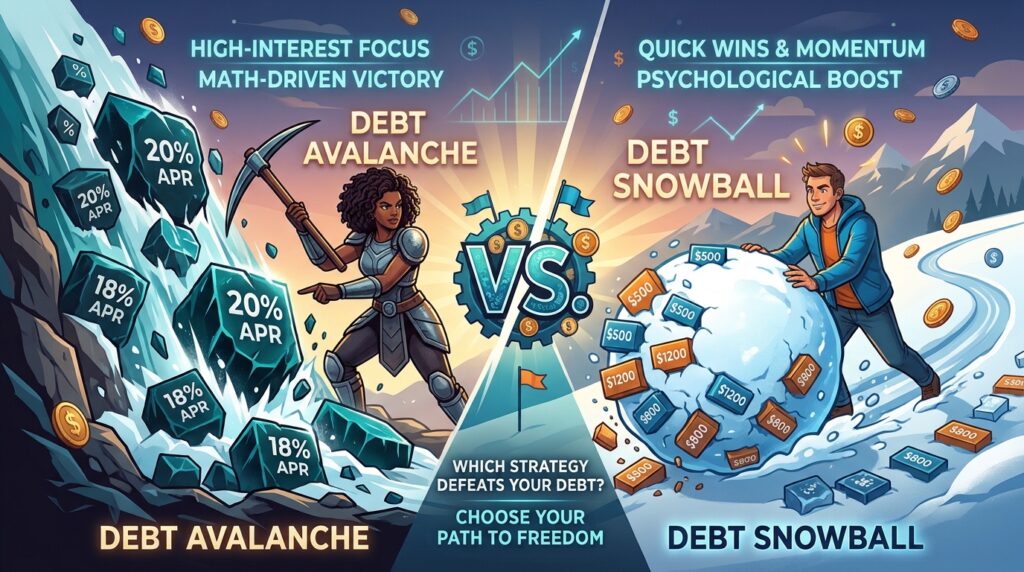
- Avalanche: pay the minimum on everything, then put every spare dollar on the debt with the highest interest rate. When it is gone, move to the next highest.
- Snowball: pay the minimum on everything, then put every spare dollar on the smallest balance. When it is gone, roll its payment into the next smallest.
Same debts, two plans
The setup
- Store card: $1,200 at 9.9%, minimum $40
- Card 1: $5,500 at 24.9%, minimum $140
- Card 2: $3,000 at 19.9%, minimum $90
Total budget: $600 a month. In the first month these debts add $173.78 of interest between them.
Avalanche result
Extra money goes to Card 1 first. It is cleared in month 14, Card 2 in month 19 and the store card in month 20. Total interest: $1,732.63.
Snowball result
Extra money goes to the store card first. It is gone by month 4, Card 2 by month 10 and Card 1 in month 20. Total interest: $2,071.74.
Both plans finish in 20 months, because the total monthly budget is the same. The avalanche saves $339.11 of interest. The snowball delivers its first win ten months sooner.
Which one should you choose?
If you are confident you will stick to the plan, the avalanche is mathematically better every time, and the gap grows with bigger balances and wider rate differences.
If you have tried before and stalled, the snowball’s early wins can be worth the extra cost. Closing an account in month four is a strong signal that the plan is working. A plan you finish beats a cheaper plan you abandon.
A hybrid is fine too: knock out one tiny balance for a quick win, then switch to avalanche order.
Things that matter more than the method
- The size of the monthly budget. Adding even $50 a month shortens either plan noticeably.
- No new charges. Both plans assume balances only go down.
- Lower rates where possible. A balance transfer or consolidation loan at a lower rate can beat both methods, but check the fees.
Frequently asked questions
Can I use the debt payoff calculator for several debts?
Run each debt separately to see how long it takes at its own payment, then use the order from your chosen method for your extra money.
What if two debts have similar rates?
Then the methods behave almost the same. Pick the smaller balance for the quicker win.